Performance Analysis of ICICI, HDFC, and Axis Banks After Q2 Results


The latest quarterly results of India's three largest private-sector banks have shown varied performance, offering insights for investors. ICICI Bank, HDFC Bank, and Axis Bank disclosed their financial results for the September quarter of Fiscal Year 2027, showcasing contrasting metrics in earnings and asset quality. ICICI Bank has reported a considerable 20.1% year-on-year increase in its standalone net profit, amounting to ₹14,843 crore. This robust growth is attributed to a substantial rise in net interest income, which climbed 17.7% to ₹25,339 crore. The bank’s net interest margin, however, saw a minor reduction of 12 basis points sequentially, settling at 4.18%. Nuvama Institutional Equities, a reputable brokerage firm, has maintained a ‘Buy’ rating for ICICI Bank with a target price of ₹1,850. Analysts at Nuvama pointed out an impressive credit growth of 30% year-on-year, coupled with an operating expenditure reduction, which allowed for a profit exceeding expectations by 7%. Looking forward, Nuvama anticipates that strong growth will likely persist, projecting returns on assets between 2.2% and 2.3%, and a return on equity around 17% from FY27 to FY29. Similarly, Systematix Institutional Research has also affirmed a ‘Buy’ rating, increasing its target price to ₹1,750 from ₹1,700. The research noted that ICICI Bank exceeded profit projections, marking a 3.3% increase from estimates, with its domestic net interest margin remaining stable at 4.32%. HDFC Bank has exhibited a more tempered growth trajectory, reporting a modest 4.7% year-on-year increase in net profit to ₹19,510 crore. The bank faced pressures on net interest margin, declining by eight basis points to 3.32%. Nevertheless, its gross non-performing asset ratio improved marginally to 1.11%, indicating enhanced asset quality. HDFC Bank is also preparing for a leadership transition, as Anup Bagchi is set to assume the role of managing director and chief executive. This transition comes at a pivotal time when the market is assessing management stability. Nuvama has retained a ‘Buy’ rating with a target price of ₹950, noting that the quarter’s results were generally in line with expectations, although management stability will be crucial for future growth. Similarly, Systematix has maintained its ‘Buy’ rating with a target price of ₹875, highlighting consistent cost of funds. In contrast, Axis Bank reported a strong 37.6% year-on-year increase in its net profit, reaching ₹7,003 crore. While its net interest income rose by 12% to ₹15,371 crore, its net interest margin settled at 3.36%. Despite reporting lower treasury gains and increased staff costs, Nuvama has kept a ‘Buy’ rating with a target price of ₹1,650. Axis has demonstrated a commendable credit growth of 22% year-on-year, although it experienced a sequential decline in net interest margin by 10 basis points. Analysts suggest that the bank's strong credit momentum, along with anticipated margin recovery, bodes well for the future. Overall, brokerage assessments portray a cautious optimism towards all three banks, with ICICI Bank being favoured for its superior credit growth and return ratios. HDFC Bank could offer recovery potential amid management changes, and Axis Bank's strong credit dynamics and expected margin improvement are encouraging signs for investors. The brokerage perspectives provide comprehensive insight as each bank adapts to industry challenges and evolving market conditions. Investors are advised to approach these stocks with an eye on individual performance metrics and broader economic conditions.
Challenges in Regulating Cancer Drug Prices Highlighted
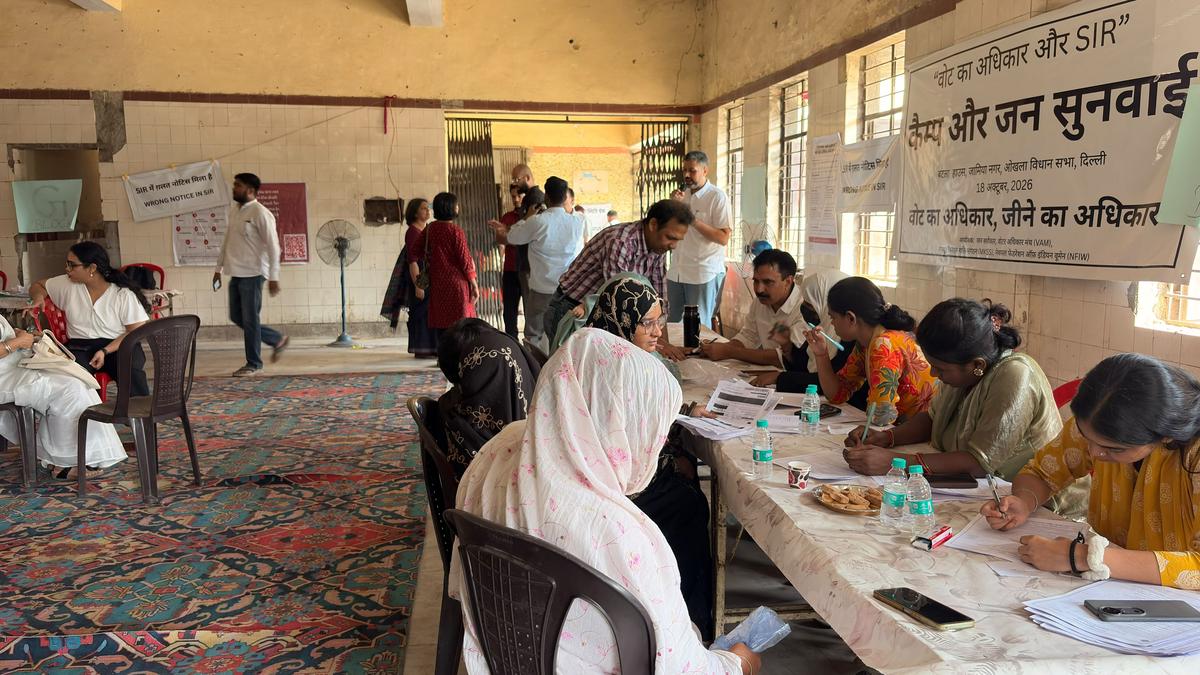
Concerns Raised Over Independent Commission Reviewing Electoral Rolls
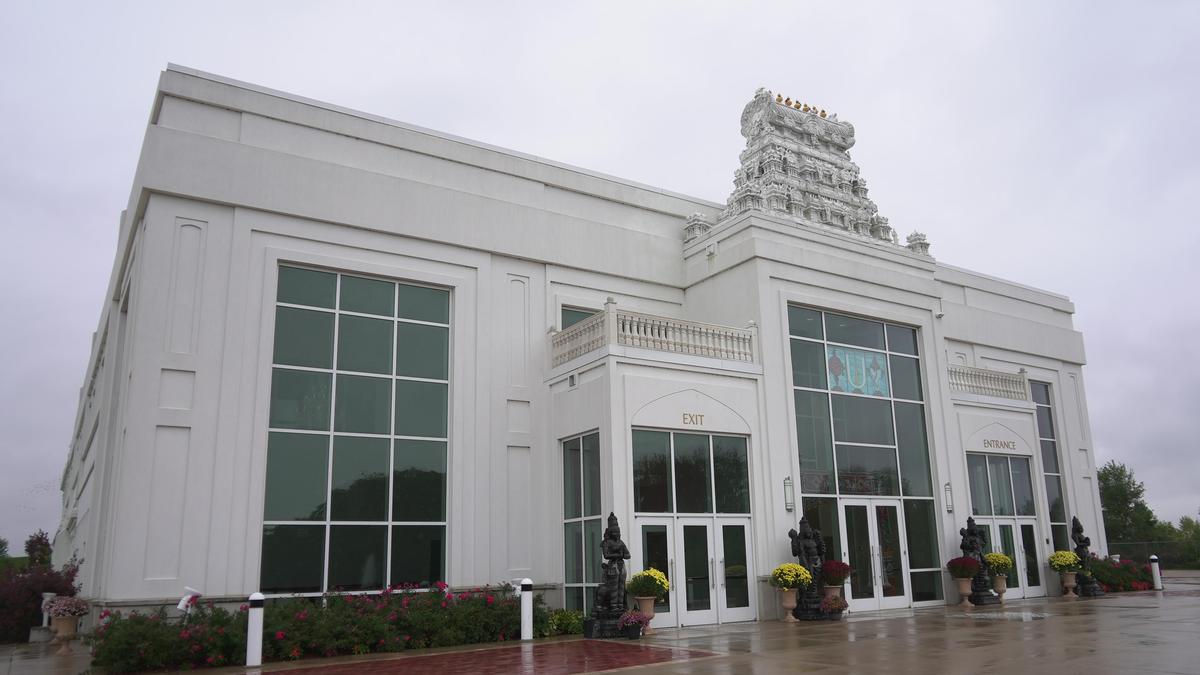
Concerns Raised Over Safety of Indians After Foiled Temple Attack
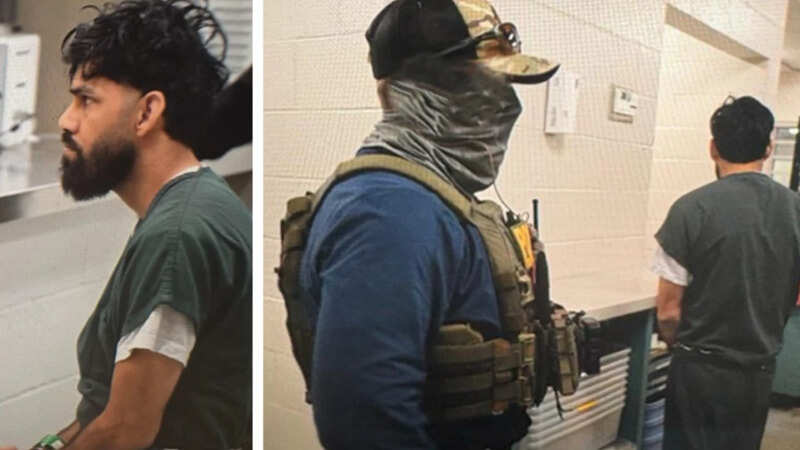
Indian National Returned to Jail in Oregon Following Fatal Crash